Home Loans & First Home Buyers
Borrowing power explained in plain terms, help with any grants you qualify for, and someone walking the application through with you from pre-approval to settlement.
Home, Investment, SMSF, Commercial and Equipment Finance, guided by 38 years of experience and a standard of service the banks don't offer.
A reputation built one client at a time. Here's what they say.
"Awesome service! Scott guided me through the whole process, making sure I understood everything. Everything was explained clearly before moving forward, barely had to lift a finger. Would highly recommend!"
"Scott is incredibly professional, approachable, and genuinely cares about his clients. He made the whole process seamless and stress-free, with excellent communication throughout. I can't recommend Scott highly enough."
"Scott was so easy to work with and made everything simple. Clear and timely updates, quick responses to texts and calls, brilliant outcomes!"
Whether it's your first home or your next development, the loan should suit your goals, not whatever the bank happens to be selling that month.
Borrowing power explained in plain terms, help with any grants you qualify for, and someone walking the application through with you from pre-approval to settlement.
Investment strategy, cash-flow analysis, and lending terms negotiated so your portfolio works harder than it otherwise would.
Vehicles, machinery, trucks, trailers, forklifts and specialised industry gear, new or used, set up so your capital keeps working rather than sitting idle.
A proper look over your current lending, with debt consolidation or restructuring where it eases repayments and frees up cash flow.
Finding lenders who actually have appetite for your project, whether that's a small subdivision or something considerably bigger.
Competitive loan products for buying investment property through a self-managed super fund, set up correctly from day one.
Finance for farming and agribusiness across Gippsland, from land and livestock to machinery and seasonal cash flow, with lenders who understand how a farming year actually works.
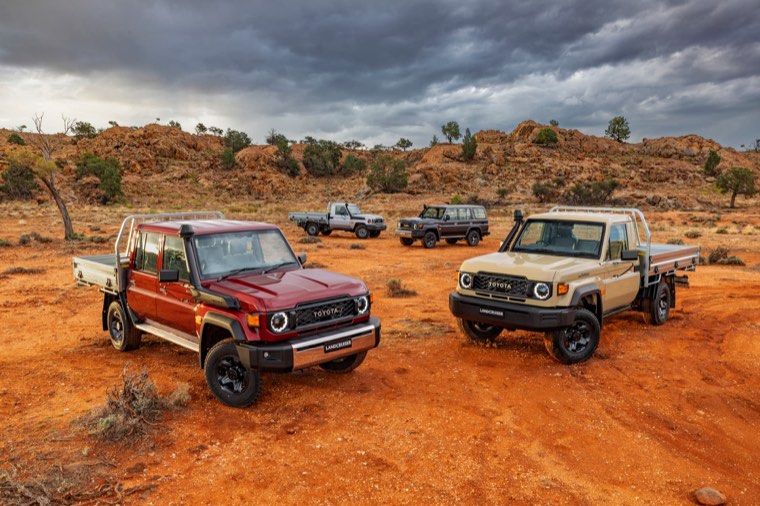
The family home, the work ute, the machinery that keeps the business running. Scott helps you secure the finance to make it happen.
"Clients deserve tailored, transparent strategies that work for them, not just the lenders."
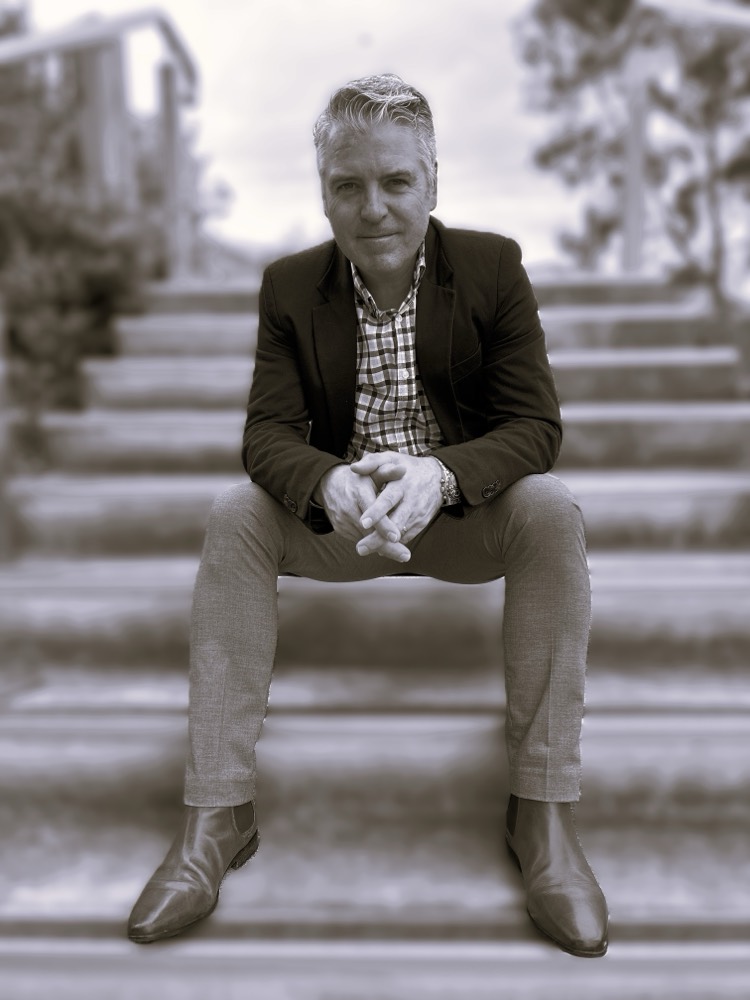
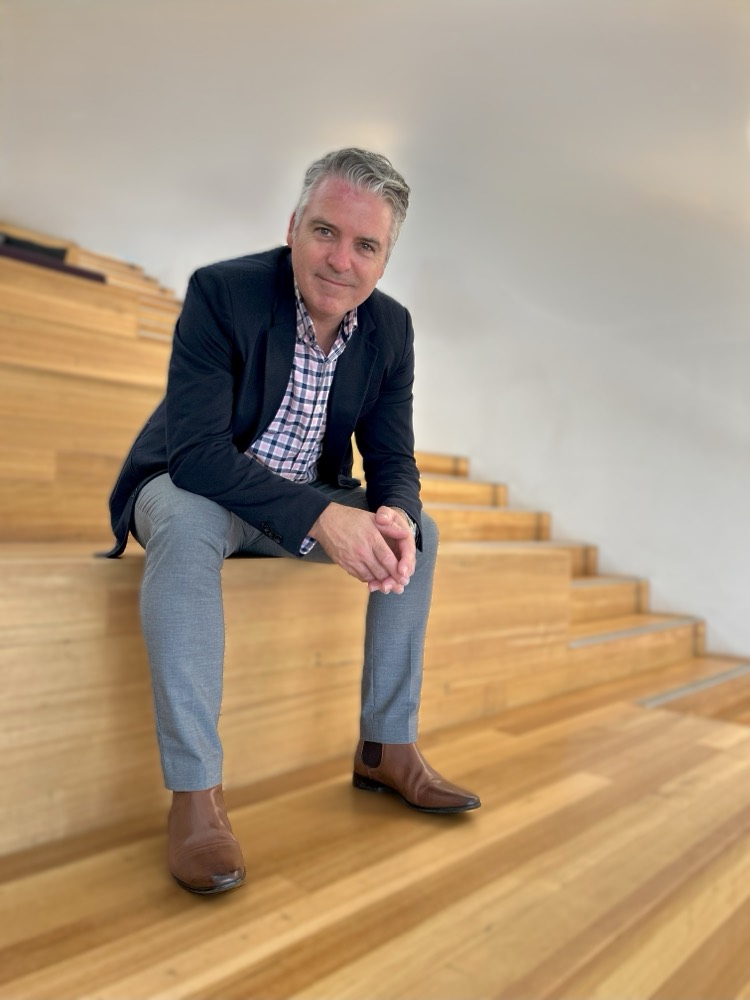
Scott brings nearly two decades inside the banks and more than twenty years as an accredited mortgage broker to every loan he writes. That depth means fewer surprises, sharper structuring, and lending advice built around what's right for you. Based in Sale, Scott works with clients across Gippsland, throughout Victoria and Australia-wide.
Straight answers to the questions borrowers ask most. If yours isn't here, just ask.
No. Scott does not charge clients a fee, on any deal. Not on standard home loans, and not on the complex or non-standard lending that some brokers do charge for. He is paid a commission by the lender once your loan settles, and that commission is disclosed to you in writing before you proceed. You will never be invoiced for his time.
A bank can only offer its own products. A broker compares options across a panel of lenders, so your loan is matched to your circumstances rather than to one institution's range. Australian brokers are also legally required to act in your best interests, which is a duty the banks' own staff do not carry.
Borrowing capacity depends on your income, existing debts and commitments, living expenses, credit history and the lender's own assessment criteria, and it can vary significantly between lenders. Scott can run the numbers across a panel of lenders and tell you where you stand, and often what could be adjusted to improve it, before you apply.
A 20% deposit avoids Lenders Mortgage Insurance, but many buyers purchase with less. Eligible first home buyers may be able to buy with as little as 5% under government guarantee schemes. Eligibility criteria and lender policies apply, so it is worth checking your position before you start looking.
Depending on your circumstances and the property, these can include the First Home Owner Grant, stamp duty concessions in Victoria, the First Home Guarantee and the First Home Super Saver Scheme. Eligibility rules change and vary by state, so Scott will check what currently applies to you and help with the paperwork.
Yes. Self-employed and business clients are a large part of what Scott does. Lenders typically look for two years of tax returns, BAS and profit and loss statements, though some will consider a shorter trading history or alternative documentation. The key is presenting your income to a lender whose policy actually fits your situation.
It depends on whether certainty of repayments or flexibility matters more to you, and on what you expect to do with the loan over the next few years. Many borrowers split their loan to get some of both. Scott will talk through the trade-offs in plain terms so you can make the call with your eyes open.
LMI is a one-off insurance premium that protects the lender, not you, and it generally applies when you borrow more than 80% of the property's value. It can sometimes be avoided with a larger deposit, a family guarantee, an eligible government guarantee scheme, or through professional waivers that some lenders offer to certain occupations.
Often, but not always. It depends on your current rate and structure, any break or exit costs, how long you plan to keep the property and what you want the loan to do for you. Scott reviews your existing lending and will tell you honestly if staying put is the better option.
Yes. Alongside home loans, Scott arranges rural and farm lending, commercial lending and asset and equipment finance for vehicles, trucks, trailers, tractors, construction machinery and specialised industry equipment, new or used.
In many cases yes, and Scott can access competitive SMSF loan products. Because SMSF borrowing has strict compliance requirements, you should speak with your accountant or financial adviser first to confirm the structure is set up correctly and that the strategy suits you.
Strategic Pathway Finance is based in Sale and works with clients right across Gippsland, including Traralgon, Bairnsdale, Warragul, Moe, Morwell and Leongatha, as well as throughout Victoria and nationally where required. Distance is rarely an issue: most of the process can be handled over the phone, by email, or on a video conference call at a time that suits you.
It varies by lender and how complex your situation is. Pre-approval is often turned around within days once your documents are in, with formal approval and settlement following the contract timeline. Scott will give you a realistic timeframe for your lender and keep you updated at each stage.
Just a conversation, with no obligation. From there Scott will tell you exactly which documents are needed, which usually means identification, income evidence and a picture of your expenses and existing debts, and will guide you through each step to settlement.
A no-obligation conversation costs nothing and could save you a great deal. Call directly, or send a message below.
A few details is all it takes. Scott will come back to you personally.
Thanks for getting in touch. Scott will come back to you shortly.
Need it sooner? Call 0429 432 600
Finance, explained simply.
Short videos on loans, lending and the questions clients ask most.